All Categories
Featured
The Mechanics of Whole Life Coverage
Table of Contents
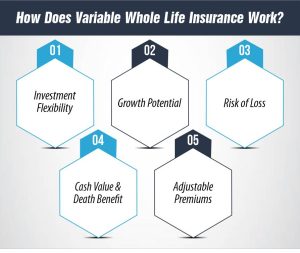
As soon as the first premium is paid, the whole survivor benefit is set aside for your family. Income tax-free death advantage: The survivor benefit of a life insurance coverage policy is not usually subject to federal income taxes. Tax-deferred development: The development of cash worth within entire life insurance coverage is tax-deferred while the funds stay in the policy.
This means withdrawals to the extent of cost basis are thought about an earnings tax-free return of cost basis. Tax-favorable access to cash worth loans for any reason: During the insured's life, money value loans taken against an entire life policy are not considered to be a taxable occasion, despite the fact that the policy may have a big gain in excess of premiums paid.
Medicare in OceansideSelf-funding: The policy can pay for itself gradually by applying dividends to pay premiums, which adds to the policy's savings component. Impairment security: An entire life policy can continue to be moneyed even if you are handicapped. When you elect the Waiver of Premium rider9, if you suffer a qualifying disability, your policy will continue to provide survivor benefit protection, have money worth growth, and pay dividends even while you aren't paying premiums.

10Distribution: If appropriately executed, life insurance helps prevent probate and can offer recipients with higher personal privacy than might be afforded by a will; a will becomes public as soon as probated, whereas survivor benefit circulations are typically personal, contractually driven transactions. Once a policy loan has been taken, the annual dividend can be used to assist pay back the policy loan.
Features, provisions, and costs vary from one insurer to the next, and each whole life contract is special to the policyholder. Entire life insurance rates depend upon aspects such as age, health, and protection amount, so it is very important to think about these when examining policies. Normally speaking, there are 2 standard types of payment structures for whole life: Level premium whole life: This is the most typical type of entire life insurance.
Medicare in OceansideEvaluating PPO vs HMO Insurance Plans
Restricted payment entire life: This type of policy has a set level premium like a level premium entire life policy, however the premium is only payable for a fixed time period. The advantage is that they are guaranteed to be paid up at the end of the payment period, so no payment is required at later ages.
Their accessibility and cost depends upon the policy and the insurance provider. In addition to the Waiver of Premium rider pointed out above, some other choices provided by Guardian include: Paid-Up Additions Rider: The PUA rider can assist increase the build-up of tax-deferred money worths and survivor benefit. The greater the premium paid into the rider, the greater the defense managed by the policy.
It offers you a distinct chance for index-linked upside potential and the floor guarantees that your year-to-year drawback market exposure is restricted. Accidental Death Advantage: Provides an additional death advantage if death happens by unintentional bodily injury. Accelerated Benefit Rider: Provides accelerated advantages, enabling you to access a part of the death advantage early if you are detected with a persistent or terminal health problem.
Individual Health Insurance Plans for 2026
Surefire Insurability Alternative (GIO): Gives the policy owner the right to purchase additional insurance coverage without proof of insurability. The GIO can become a lot more important in case of special needs: An insured who is disabled and has their premium waived may exercise the GIO rider, and Guardian will pay the premium on the brand-new policy An entire life insurance policy is among the most important monetary purchases you can make.
12 Comparing life insurance coverage companies and their life insurance offerings such as entire life, universal life, fixed premiums, guaranteed survivor benefit, and cash worth development is vital to finding the right policy for your requirements. There are trusted, independent sources for financial strength ratings, such as A.M. Best, Moody's, Requirement & Poor's and Fitch.
Discuss your scenario with an insurance coverage expert or financial professional who comprehends whole life insurance coverage and can direct you to the service that finest meets your needs. If you do not understand such an expert, ask a buddy or associate for a recommendation. Or, Guardian can link you to a monetary professional who can help.
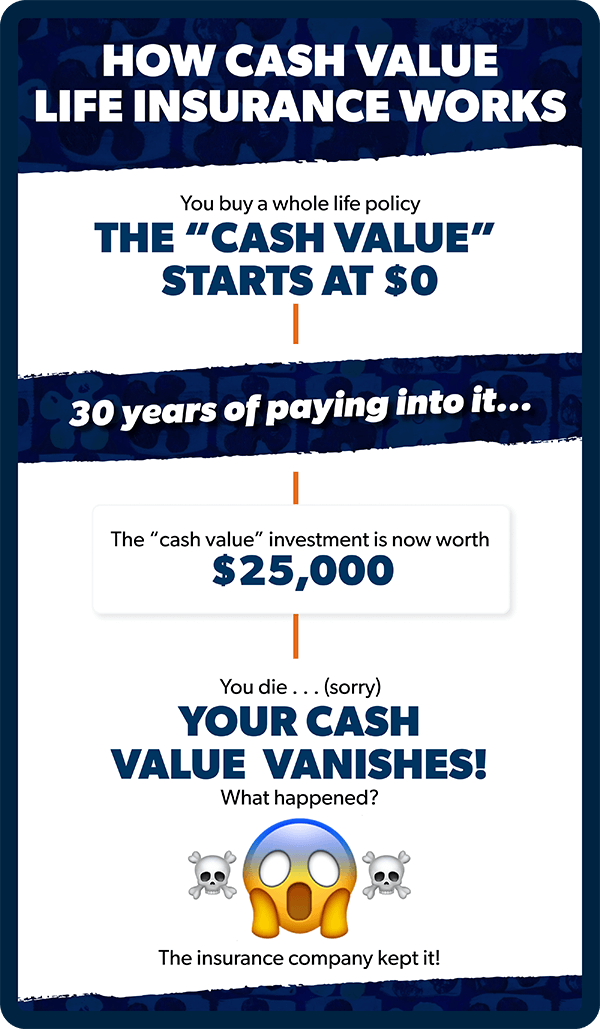
A whole life policy has money value that grows over time. You can cash it out to assist supplement retirement, or obtain versus it at any time, for any factor. Entire life policies have a component described as the policy's cash worth: A portion of your premium dollars can grow in time on a tax-deferred basis, so you do not pay taxes on the gains.

Latest Posts
Choosing HMO or PPO Health Insurance Plans
Planning Expense and Burial Insurance for Seniors

Strategies for Affordable Medical Coverage